The five main disadvantages are mileage limits, no equity, return charges, perpetual payments, and costly early exits. Each drawback can shrink a lease’s apparent savings or limit your choices later. Together, they can turn an affordable-looking deal into an expensive, inflexible commitment over time.
Still, these problems do not make every lease unwise. They matter when the contract conflicts with your mileage, budget, or ownership plans. Before signing, compare the total obligation rather than focusing only on the monthly payment. Then convert each risk below into a specific contract question.
1. Mileage Restrictions and Excess-Mileage Penalties
Most leases cap the miles you may drive annually or across the entire term. Therefore, extra driving can trigger mileage penalties when you return the vehicle. The contract sets your allowance, calculation method, and per-mile charge. Only those written terms define your real exposure.
Your commute provides the baseline, but ordinary life creates additional miles. Weekend errands, school trips, vacations, and family needs can quickly consume a narrow allowance. Furthermore, a new job or longer commute may disrupt your original estimate. Drivers with variable schedules face the greatest uncertainty.
Estimate your needs from service records and odometer readings, not memory. First, calculate commuting miles across your actual working days. Next, add routine errands, seasonal travel, and a sensible buffer. Finally, compare that total with every available mileage tier.
Compare prepaid-mile pricing with the lease-end rate before choosing. Then monitor your odometer quarterly against the planned pace. Consequently, you can adjust optional driving before a small gap becomes expensive. Never assume a dealer will waive mileage penalties.
2. You Build No Ownership Equity
Lease payments purchase temporary vehicle use rather than ownership. Therefore, you usually return the car without an asset to sell. A financed purchase works differently because each payment moves you toward ownership. Eventually, the owner may enjoy years without loan payments.
No ownership equity matters most when you keep dependable vehicles for many years. Conversely, frequent vehicle changers may value predictable turnover more than future equity. Your actual habits should drive the comparison.
Do not compare only monthly payments. Instead, include upfront charges, insurance, maintenance, taxes, end costs, and the purchased vehicle’s remaining value. Treat any lease-end buyout as a fresh purchase decision. Its residual value may not match the vehicle’s market value.
Review the advantages that balance these tradeoffs before rejecting leasing completely. Lower payments or newer technology may still support your priorities. Nevertheless, those benefits should solve a real need.
3. Wear-and-Tear Charges at Return
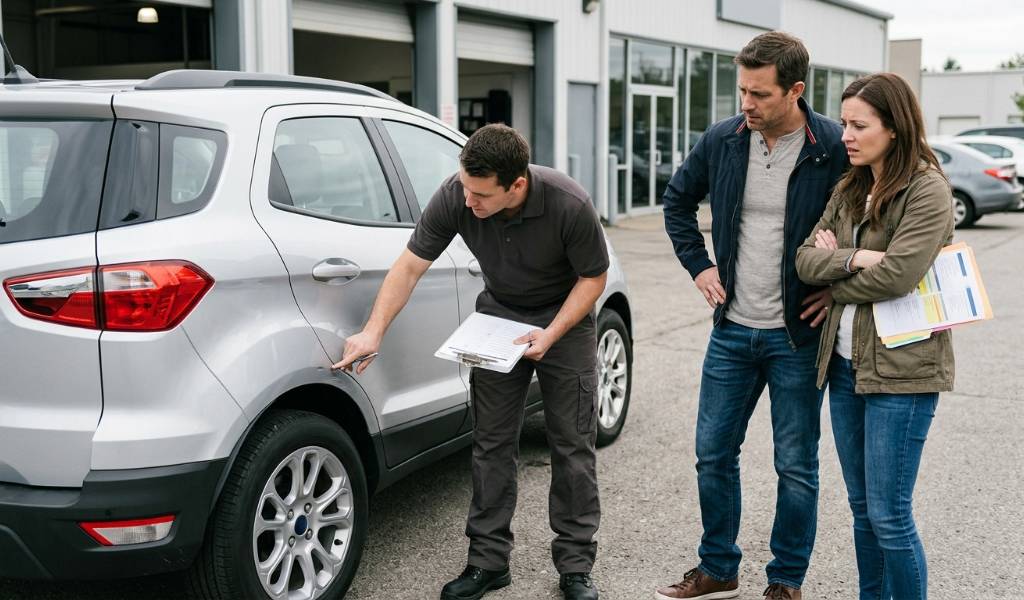
Lessors expect normal use, yet contracts define acceptable condition differently. Damage beyond those standards can trigger excess wear charges. Common concerns include deep scratches, dents, cracked glass, damaged wheels, stains, and missing equipment. Worn tires or neglected maintenance may also create costs.
Customization limits create another return risk because modifications may violate the agreement. Therefore, obtain written permission before changing paint, suspension, accessories, or electronics. Even reversible work can leave damage after removal.
Protect yourself with records throughout the term. Keep maintenance receipts, dated photographs, repair invoices, and every inspection report. Additionally, follow the manufacturer’s service schedule and retain every key.
Request a pre-return inspection when the lessor offers one. This step gives you time to compare repair estimates with potential charges. However, fix only damage that the written standards classify as chargeable. Cosmetic repairs can cost more than the lessor’s assessment.
4. Higher Lifetime Cost If You Lease Forever
One lease can fit a temporary need, but repeated leases create perpetual payments. Buyers may finish a loan and continue driving without monthly principal payments. Serial lessees restart acquisition costs and monthly obligations with each replacement. Consequently, short-term affordability may undermine long-term savings.
Ownership still brings depreciation, repairs, and maintenance. Therefore, neither path guarantees the lowest lifetime cost for every driver. Compare the same vehicle class, timeline, fees, insurance, maintenance, taxes, and resale value.
Before renewal, compare three realistic paths. This review prevents convenience from sustaining an unsuitable payment cycle:
- Start another lease with clearly stated drive-off costs.
- Buy the current vehicle after evaluating its total purchase cost.
- Purchase another vehicle and plan a practical ownership period.
Then calculate each option across several years, not merely the next month. Use conservative assumptions for repairs and resale value. Moreover, keep emergency savings separate from any projected payment reduction. A smaller payment never compensates for financial fragility.
5. Expensive to Exit a Lease Early
A lease works best when you complete its full term. Early termination costs may include remaining obligations, fees, or a payoff shortfall. Therefore, relocation, unemployment, disability, or family changes can expose serious inflexibility. A lifestyle change does not erase the contract.
Never judge an exit using verbal estimates. Ask the lessor for a dated written payoff and the permitted alternatives. Then compare total costs for termination, transfer, trade, or purchase. Taxes and administrative fees can change the result.
A qualified driver may assume some leases, but lessors can restrict transfers. Therefore, read every condition and confirm ongoing responsibility before paying a transfer service. A buyout followed by resale may also work. However, taxes, fees, timing, and selling expenses can erase any gain.
Sign only for a term that suits foreseeable plans and stable income. Likewise, avoid large upfront payments merely to lower the monthly figure. An accident or early exit can jeopardize that money.
Who Should Think Twice About Leasing
Leasing creates the most friction for drivers with unpredictable mileage or rough daily use. Pet owners, parents, rideshare drivers, and frequent travelers may face added condition or mileage exposure. Meanwhile, enthusiasts may dislike strict customization limits. Long-term keepers lose the most from repeated nonownership.
Income uncertainty, a planned move, or changing family size can make a vehicle unsuitable early. Similarly, expensive insurance requirements can undermine an attractive payment. These patterns may magnify several disadvantages simultaneously.
Still, one risk factor does not automatically rule out a lease. Examine leasing a car through your real routine, not an ideal month. Then reject any contract that depends on optimistic assumptions.
Use this decision check before signing. Each answer should rely on your records and written contract terms:
- Does the mileage allowance cover normal driving plus a realistic buffer?
- Can the budget absorb insurance, maintenance, and likely return charges?
- Does the term match foreseeable work, housing, and family changes?
- Would ownership create more value across your expected driving horizon?
- Can you follow every condition and customization rule comfortably?
Frequently Asked Questions
What Is the Biggest Downside of Leasing a Car?
The biggest downside usually involves paying for use without building ownership value.
Can You Negotiate Mileage Limits on a Car Lease?
You can often choose another mileage tier, but the lessor controls available terms and pricing.
Is Leasing Bad for High-Mileage Drivers?
Leasing often costs high-mileage drivers more because excess miles can trigger contract charges.
Can You Avoid Wear Charges by Buying the Leased Car?
A buyout may change the return process, but your contract still controls every outstanding obligation.
Can You End a Car Lease Early Without Penalties?
Some transfers or buyouts may reduce costs, but few contracts promise a penalty-free early exit.
Turn Every Drawback Into a Contract Check
The five drawbacks become manageable only when you price them before signing. Compare those findings with the full contract, not the advertised payment. Then walk away whenever the numbers require perfect behavior or perfect luck.
Finally, ask the lessor to explain every uncertain term in writing. Compare at least two offers using the same mileage and upfront cash. Choose the agreement that fits your actual life, or choose ownership instead. Take that final contract check before committing your money.
Thomas Walker is an accomplished writer with expertise in the basics of car accessories. With a keen eye for detail, Thomas has established himself as an authority on the subject, with a passion for all things automotive. Based in Jasper, Thomas is dedicated to providing readers with the information they need to make informed decisions when it comes to their car accessories.